Desk story / Payments
Credit Card Deposits at Online Casinos: Pros and Cons
Credit card deposits are the easiest way to fund a casino account. They are also the way that most people accidentally go into debt gambling.
- Filed
- Byline
- Cole Hastings
- Length
- 561 words, about 3 minutes
- Copy ID
- SM365-D921C77E
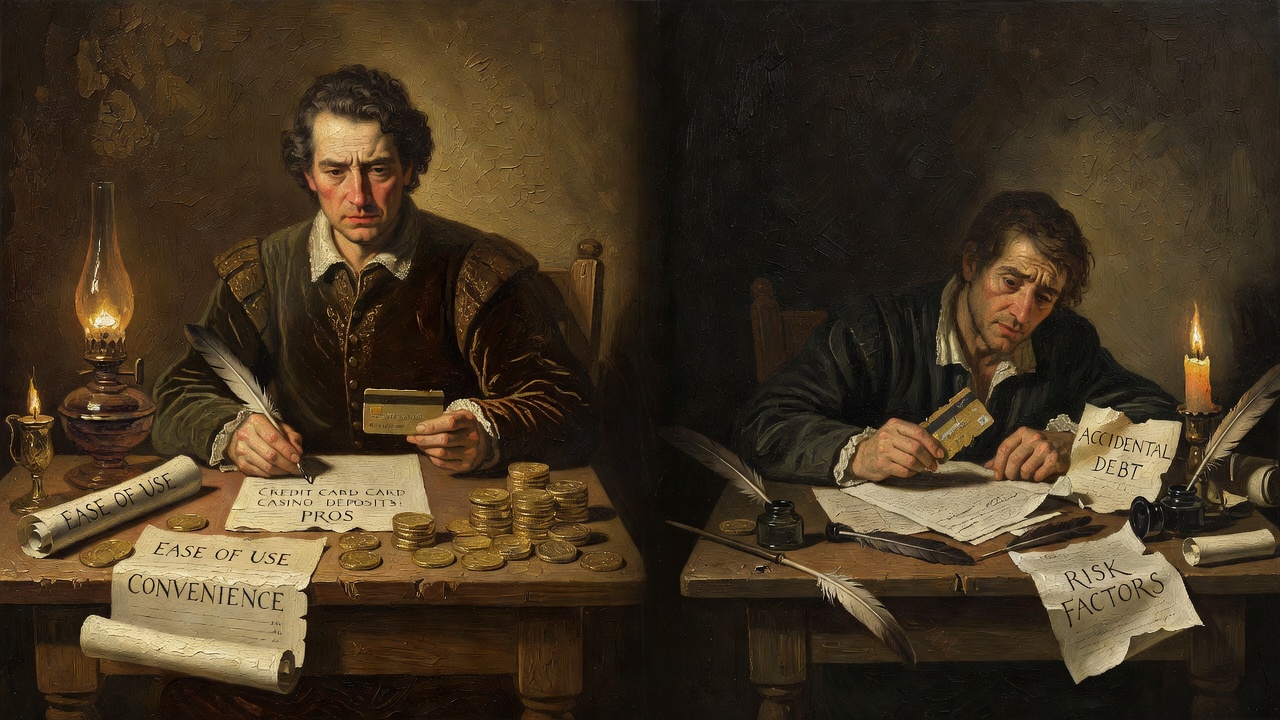
The credit card is a line of credit. You use it to pay for a thing. The bill comes at the end of the month. You pay the bill. Unless you do not pay it. Then interest accrues. Credit card interest is typically 18 to 22 percent annually. A player who deposits two hundred dollars and does not pay it off immediately is paying interest on gambling losses.
Casinos love credit card deposits because the system is familiar and frictionless. A player enters their card information. Funds are immediately available. The player can gamble without delay. From the casino's perspective, speed of access equals revenue generation.
Credit card companies are increasingly skeptical of gambling deposits. MasterCard and Visa have tightened their policies on gambling merchants. A casino that was previously able to process deposits as entertainment is now required to process them as gambling. The distinction matters for regulatory oversight.
The drawback of credit card deposits is the temptation. A player with a two-thousand-dollar credit limit can deposit two thousand dollars and lose it. The money is not coming from the player's bank account. It is coming from the credit card company. The player feels the loss less acutely because the money was never truly theirs in the first place.
Some casinos deliberately encourage credit card use because they understand this psychology. A fast approval, a high limit, a simple interface. These are all designed to minimize the friction between the impulse to gamble and the act of depositing. The faster the deposit process, the less time for reconsideration.
The Problem With Debt Gambling
When you gamble with borrowed money, you are playing with money that you owe interest on. A five-hundred-dollar loss becomes a five-hundred-dollar debt. If you do not pay it off in full the next month, interest accrues. After six months, the five-hundred-dollar loss has become six-hundred-and-fifty dollars of debt. The casino won. The credit card company won. The player lost twice.
Regulatory evolution has pressured casinos to discourage credit card use. The UKGC now requires that operators warn players about credit card deposits. Some operators have implemented limits: a player cannot deposit more than fifty pounds via credit card without additional verification. This friction is intentional.
Other operators have moved away from credit cards entirely. They prefer bank transfers, e-wallets, and cryptocurrencies because these methods create more friction. A player making a bank transfer has to think about it. A player using a credit card does not. The immediacy of credit cards makes them dangerous for players who are not disciplined.
The alternative is a debit card, which draws directly from a bank account. Debit card deposits create immediate consequences. A player loses one hundred dollars via debit card and their bank account is one hundred dollars lighter. The loss is concrete. With credit cards, the loss is abstract until the bill arrives.
An intelligent gambler uses debit cards and avoids credit card deposits entirely. The friction of having to wait for bank transfers or having to verify identity is a feature, not a bug. The friction is your protection against impulse gambling and against accumulating debt you cannot afford.
The credit card companies know this. Visa and MasterCard have been gradually restricting how their cards can be used for gambling, partly out of concern for consumers and partly to protect themselves from fraud disputes and chargebacks.